Pag-IBIG Fund's ₱10 Million Loanable Program, Explained
This is the single biggest reason more buyers can now afford a unit at Coast Residences. Here's how the program works, in plain terms.
Note on figures: Pag-IBIG Fund periodically updates its loanable amounts, interest rates, and eligibility rules — this particular ₱10 million programme has already been revised more than once since it launched in May 2026, most recently on its socialized-housing price ceilings. The numbers below reflect the program's structure as of September 2026. I confirm the exact, current rates and terms with Pag-IBIG before we submit any application together — treat this page as an orientation, not a final quote.
Why ₱10 Million Changes the Math
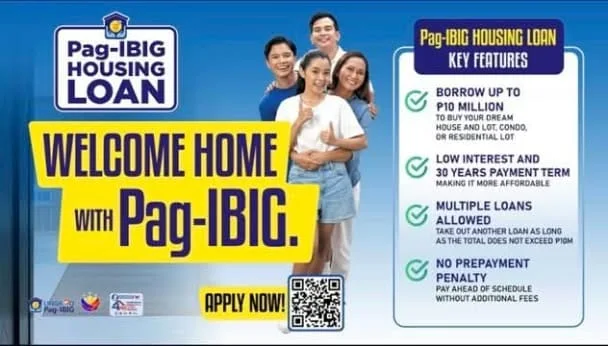
For years, Pag-IBIG's home loan ceiling sat well below what a decent condo unit in Metro Manila actually costs — pushing buyers toward bank financing with stricter approval and often higher long-term cost. Raising the ceiling to ₱10 million brings many more units, including higher-end cuts at developments like Coast Residences, within reach of a government-backed loan.
-
Higher Loan Ceiling
Loanable amounts scaled up to a maximum of ₱10 million, letting buyers finance pricier units without switching to commercial bank loans.
-
Longer Terms
Repayment terms of up to 30 years are typically available, which keeps monthly amortization manageable relative to bank loan terms.
-
Government-Backed Promo Rates
The current promo rates (4.5%–5.75%, through 31 December 2026) undercut typical bank mortgage rates. Outside the promo, Pag-IBIG's standard rate for a long fixing period can run up to 9.75% — it's specifically the promo that makes the comparison so favorable right now.
General Eligibility
Actual requirements are set by Pag-IBIG Fund and verified during application. As a starting checklist, buyers I work with typically need:
-
Membership & Contributions
An active Pag-IBIG membership with the required minimum number of monthly contributions before applying for a housing loan.
-
Age & Loan Term Fit
Applicant age plus loan term must generally fall within Pag-IBIG's maximum allowable age at loan maturity.
-
Capacity to Pay
Verifiable income — whether locally employed, self-employed, or an OFW — sufficient to support the monthly amortization.
-
No Outstanding Pag-IBIG Housing Loan
Generally, the borrower should not have an existing unpaid Pag-IBIG housing loan in default.
Pag-IBIG vs. Typical Bank Financing
A simplified comparison to frame the conversation — I'll run your actual numbers when we talk.
| Factor | Pag-IBIG Fund Housing Loan | Typical Bank Mortgage |
|---|---|---|
| Max Loanable Amount | Up to ₱10 Million | Varies by bank & borrower profile |
| Interest Rate | Promo: 4.5%–5.75% through Dec 2026; standard brackets run up to 9.75% | Market-driven — roughly 6.25%–8.75% on a 1–5 year fix |
| Max Loan Term | Up to 30 years | Commonly 15–20 years |
| OFW-Friendly Process | Established OFW loan channels | Varies widely by bank |
| Approval Basis | Membership contributions + income capacity | Primarily credit score & bank risk model |
The 4.5% / 5.75% Promo Rates
Pag-IBIG is currently running promotional rates that materially change the monthly figure, on top of the higher socialized-housing price ceilings government raised alongside them. I'll confirm the brackets still apply on the day we file.
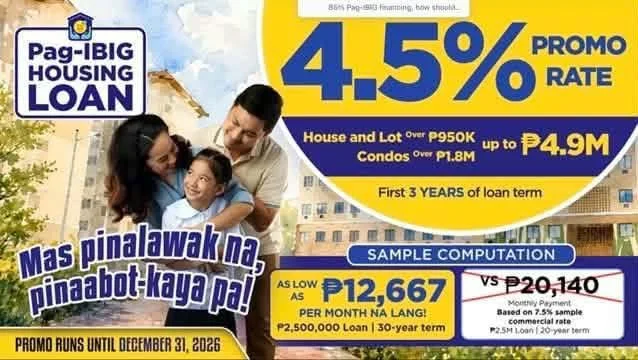
4.5% p.a., fixed for the first 3 years — loans above the socialized-housing price ceiling and up to ₱4.9 million.
5.75% p.a., fixed for the first 3 years — loans from ₱4.9 million up to the ₱10 million ceiling. Both apply to house-and-lot and condominium purchases alike.
Socialized-housing price ceilings (below which a separate, lower subsidized rate applies instead): house-and-lot up to ₱950,000; condominium up to ₱1.8 million (up to ₱2 million in NCR and other highly urbanized cities, via a location-based zonal-value add-on).
Loan-to-value: up to 95% of the property's value for loans up to ₱2.5 million, up to 90% above that.
Sample computation: a ₱2,500,000 loan over a 30-year term works out to roughly ₱12,667 a month at the 4.5% promo rate — against about ₱20,140 a month on a 7.5% commercial rate over 20 years.
Promo applications must be filed by 31 December 2026.
Sample figures are Pag-IBIG's own illustration, not a quote, and the exact price-ceiling and rate brackets have moved more than once in 2026. Your actual amortization depends on the approved loan amount, your term, and the rate and brackets in force when the loan is released — I confirm all of this before we file.
The ₱10M Ceiling Applies Across Property Types
The same Pag-IBIG programme covers house-and-lot developments, not just city condominiums — so if a unit at Coast Residences turns out not to fit your plans, the financing conversation doesn't have to start over.
Ask me and I'll map your budget against both.

How We'd Move From Here to Approved Loan
-
Check Your Pag-IBIG Standing
Confirm active membership, contribution count, and whether you have any existing housing loan.
-
Match You to a Coast Residences Unit
We shortlist units whose price fits comfortably under the ₱10M ceiling and your target monthly payment.
-
Reserve the Unit
Pay the reservation fee to SMDC and lock in the unit while we prepare loan documents.
-
Submit Pag-IBIG Loan Application
I'll walk you through the required documents — proof of income, IDs, and property documents from SMDC.
-
Loan Evaluation & Approval
Pag-IBIG evaluates capacity to pay and issues a Notice of Approval once cleared.
-
Turnover
Once the loan is released and the unit is ready, we proceed to turnover and move-in.
Not Sure What You'd Actually Qualify For?
Tell me your monthly income and target unit type, and I'll give you a realistic loanable amount estimate before we talk to Pag-IBIG.