Good news: getting started with a Pag-IBIG Housing Loan doesn't have to feel complicated. Most of what decides whether you can apply comes down to your membership, your age and your loan history, and you can check all three yourself in a few minutes.
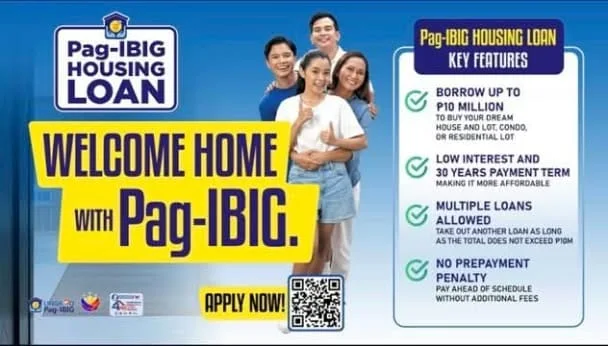
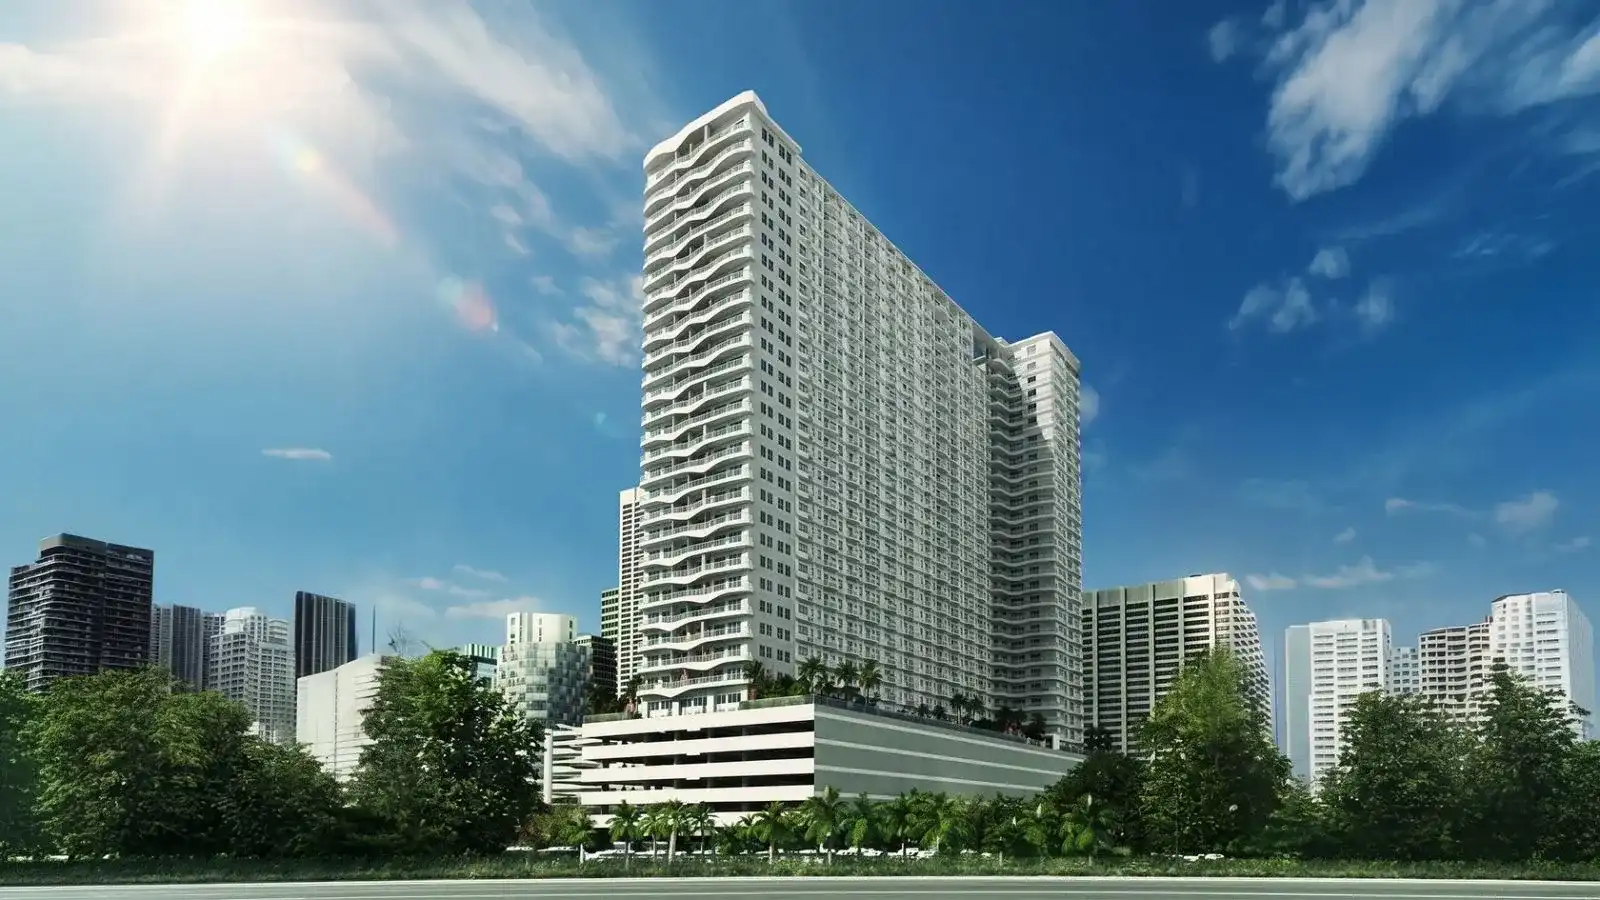
The timing is good, too. In May 2026, Pag-IBIG Fund raised its maximum housing loan from ₱6 million to ₱10 million per borrower[2], payable over up to 30 years[1]. In September, SMDC and Pag-IBIG signed an agreement opening more SMDC developments to Pag-IBIG borrowers, with preferential pricing on selected units in participating accredited projects[5].
A higher ceiling isn't automatic approval, though. Pag-IBIG still looks at your income, your debts and what the property is worth[2][3]. This guide walks through all of it: who qualifies, how much you can borrow, what it costs per month, what to prepare and how to apply.